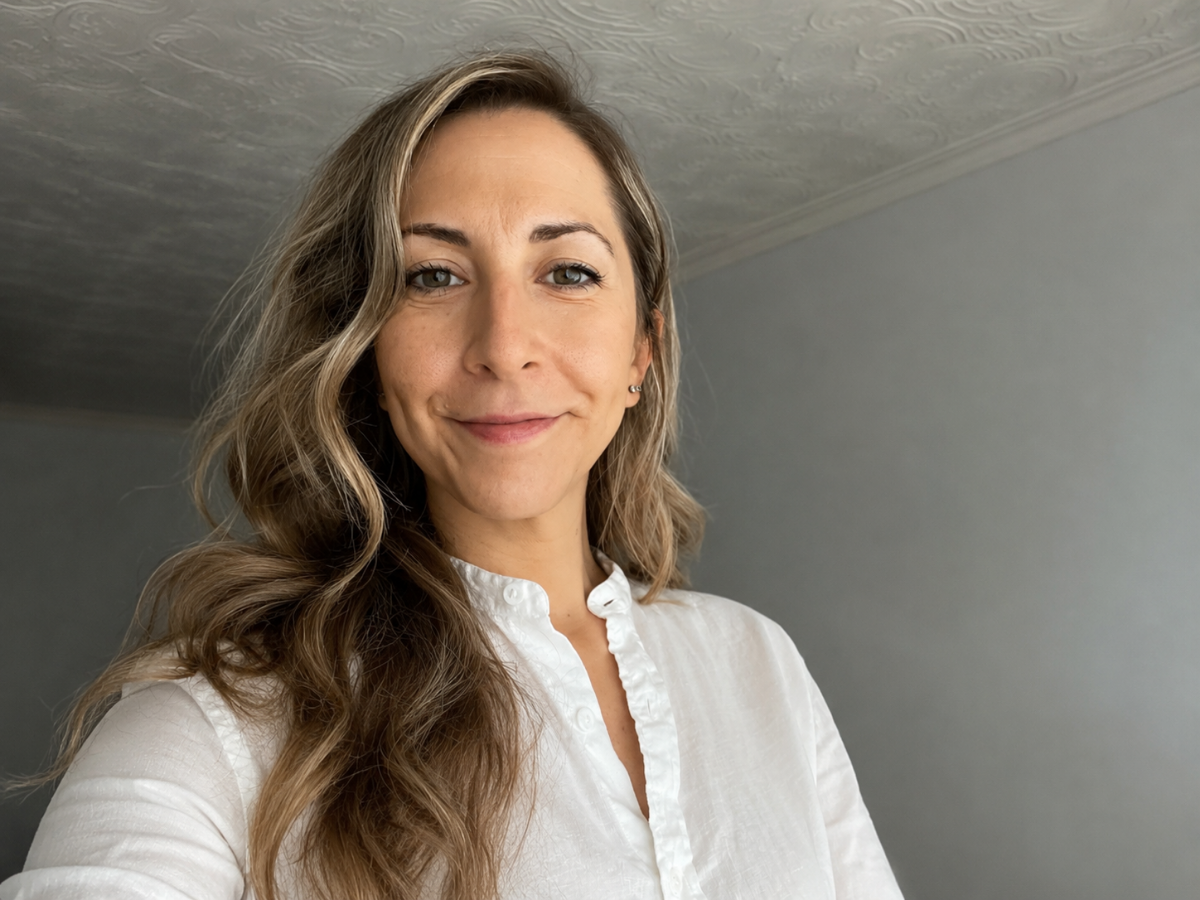
Alexis Levenson knew she found the perfect house when she saw it: a 1950s-style, semi-detached bungalow with plenty of space and light — and an unfinished basement she could easily convert into a legal secondary unit to rent out to pay off her mortgage.
In 2022, Levenson, 42, who works at a fintech startup, was looking to upgrade from her condo to a larger space while the market was down, in the hopes of starting a family soon. She made an ultimatum offer of $700,000 on a bungalow in the east end of Toronto and submitted permits to renovate the basement even before the deal officially closed in February 2023.
“I knew that I wouldn’t be able to afford the house on my own if I was to ever go on maternity leave or need to take time off work, or get fired,” said Levenson. “So, the intention was that the mortgage would be able to support me if anything happened to my full-time job.”
The extra income covers nearly two-thirds of her monthly mortgage payment plus property taxes, she said.
Levenson is part of a growing pool of homeowners using their extra space to pay off their mortgage. More than one-third of Canadians said they need to rent out part of their home to afford ownership , up from 25 per cent in 2021, according to a June report from Mortgage Professionals Canada.
“ Affordability is increasingly stretched in this economy,” said Lauren van den Berg, chief executive of Mortgage Professionals Canada. “For some of these households … renting part of the home is no longer just a lifestyle choice.”
Van den Berg said she has seen homeowners rent out secondary suites, basement units or garden suites and laneway homes, which are small additional dwelling units on a property.
And it’s a strategy that buyers such as Levenson are taking into consideration even before they move in.
Alex Blenkarn, a Peterborough-based realtor at Royal LePage Our Neighbourhood Realty, said over the past year first-time buyers have been asking him more questions about the potential for rental income as they tour properties. Even though interest rates on many mortgages have dropped to about four per cent, home prices are still out of reach, especially for Canadians buying solo, Blenkarn said.
He recounted working with a recent buyer who, as a single person, could only qualify for a property listed at less than $300,000. However, with the goal of renting out the basement, this opened options to consider properties priced as high as $400,000.
This trend also depends on region, according to the Mortgage Professionals report. The proportion of respondents who said they would need to depend on rental income made up just 19 per cent in the Prairies but climbed to 55 per cent in British Columbia.
This doesn’t surprise Adil Dinani, a Vancouver-based realtor with Royal LePage West Real Estate Services, who said an additional unit is one of the top three requirements most of his clients make. In British Columbia, the average home price was $946,431 in June, the highest across the country, compared with the national average of $696,078, according to the Canadian Real Estate Association.
Dinani usually sees this strategy among “mobile buyers,” or existing homeowners taking the next step up the property line, such as from a townhouse to a bungalow.
“It’s the peak millennial at a more progressed stage of life,” he said. “The only way to take that next step up, over 50 per cent of the time, is if they have some sort of offset from a mortgage helper.”
Dinani said if he had two equally sized listings on the market, and one had a one-bedroom legal suite that could be rented out for $1,500 a month while the other didn’t, there would be no question in his mind which would sell first.
“There’s a larger pool of buyers looking for that safety net from that mortgage helper,” he said. “We’re starting to see this evolution of homeownership .”
Dinani anticipates this trend will continue in future years, too. “It is absolutely a must for any new construction home or duplex residence to have that legal suite,” Dinani said.
Take The Trails of Lily Lake community in Peterborough, for example. It contains recently constructed, multiple two-storey homes that have fully finished basements with separate entrances.
Paul Dietrich, owner of Dietrich Homes, one of the developers in the area, said he has been building this specific type of home for the past three years with the intention of incorporating legal secondary suites, as he noticed buyers were looking for ways to offset their mortgage costs amid rising home prices.
Dietrich said his recent builds in the community have sold for $750,000 and up, compared with a couple of decades ago, when properties sold for around $75,000 and up. “That’s a tenfold increase.”
However, as prices appreciate and Canadians look for creative ways to help pay off their home loans, there are tax implications and other considerations to keep in mind.
Jamie Golombek, managing director of tax and estate planning at Canadian Imperial Bank of Commerce (CIBC) Private Wealth, said that while rental income is considered taxable income, there are a few deductions to claim. These include mortgage interest and a portion of property taxes, home insurance, utilities, repairs, and maintenance and legal fees.
And the principal residence exemption to capital gains is only applicable if you meet certain requirements, he added. The first condition is that the rental use of the home is secondary to the main use of your home.
The second condition is that you haven’t made a major structural change to create a rental unit, such as constructing a laneway home on your property, Golombek said. You also cannot claim depreciation, or capital cost allowance, on your property to be exempt from the capital gains tax, he added.
And sharing space with your tenant isn’t entirely risk-free, van den Berg said.
“Being a landlord … comes with a lot of responsibilities and additional costs.”
Homeowners renting out part of their homes may have to deal with vacancy periods, late rent payments, tenant issues and taxes and be on the ball with maintenance and repairs.
“Rental income can help, but it should be part of a realistic mortgage plan, not a way to justify taking on a mortgage that’s otherwise unaffordable,” van den Berg added.
Levenson, who has been renting out the basement of her home since September 2023, said she worked with her real estate agent.
In exchange for about one month’s rental income, her agent found and vetted her current tenants, a young couple looking to rent for a longer period of time, and Levenson did her own homework as well, through credit checks, interviews and social media screening.
At the end of the day, their landlord-tenant relationship comes down to respecting each other, Levenson said. If she is hosting a get-together, she warns her tenants about additional noise well in advance, and if she goes out of town, her tenants help with taking out the garbage.
She said she also ensures maintenance issues, such as the backed-up basement drain that meant replacing her furnace and piping last year, are taken care of as quickly as possible.
Thanks to the extra financial security, Levenson was able to achieve another dream, too: starting a family as a single mother by choice.
“I have one gorgeous daughter who’s 14 months old now, and she’s got a great big backyard to play in,” Levenson said. “I was able to have a really great maternity leave for a year, knowing that I had renters who were helping to support the payment of the mortgage.”
• Email: slouis@postmedia.com