Key takeaways:
- If you have the means, now may be a good time to buy a house.
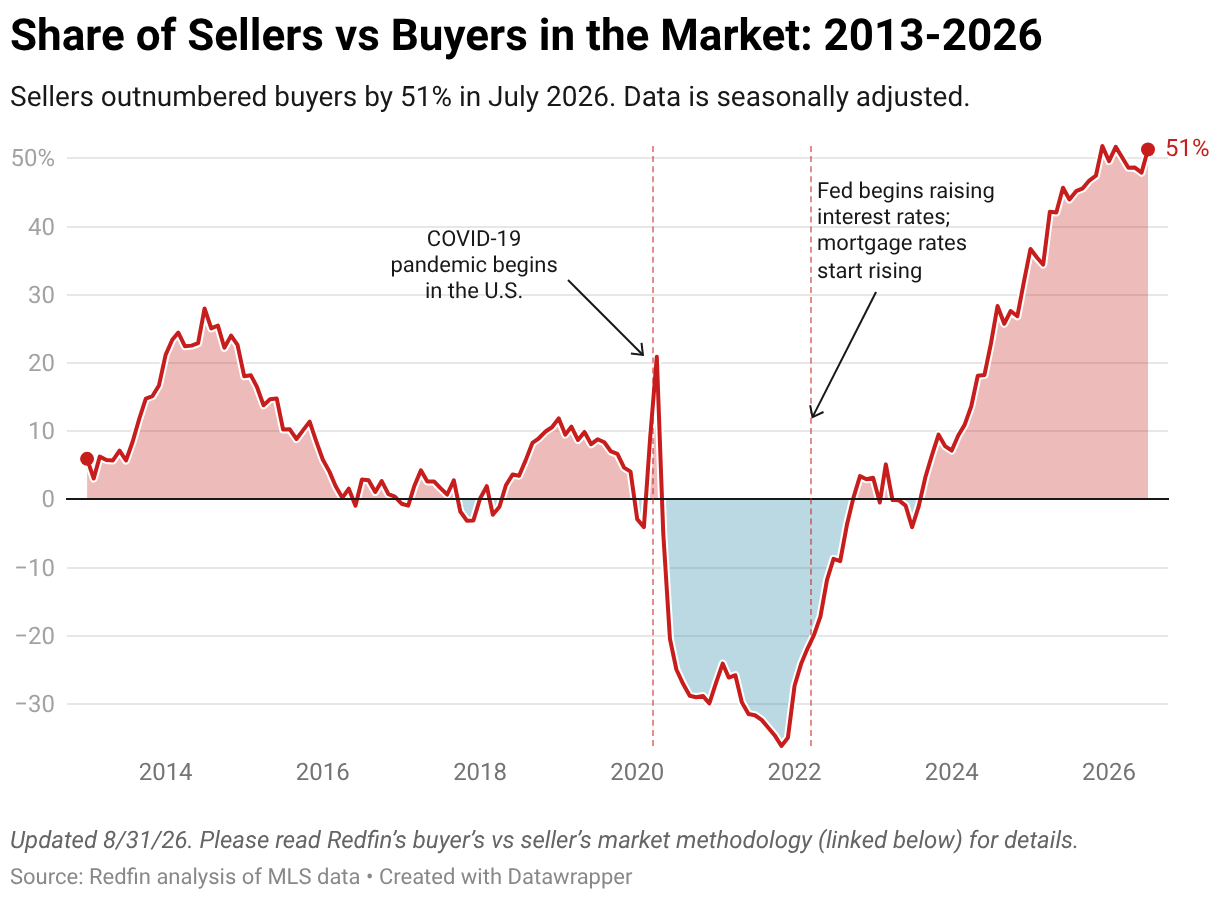
- It’s a buyer’s market—there are 51% more home sellers than buyers—giving homebuyers leverage.
- Mortgage rates are elevated and volatile due to the conflict with Iran and its effects on oil prices and inflation.
- Consumers are wary due to near-record-high housing costs, a difficult job market, and economic uncertainty.
Summer is well underway, but the housing market is still thawing from its yearslong freeze. After a very slow 2025, the same sluggish trends are persisting well into 2026: few home sales, limited listings, and near-record monthly costs.
Adding to the difficulty, mortgage rates remain elevated and volatile due to prolonged conflicts in the Middle East and their effect on oil prices. Even if a long-term peace deal were to be struck, economists don’t expect major improvements until economic pressures ease. Global economic volatility, AI fears, tariff uncertainty, and a difficult job market are all weighing on investors and consumers, keeping rates elevated.
A lot is changing, so it’s no surprise that buyers are wondering if now is the right time to take the leap.
In short, whether or not it’s a good time to buy a house boils down to if it’s a good time for you to buy a house. Let’s dive a bit deeper into today’s market trends to help you answer: “Should I buy a house now or wait?”
From Redfin’s Chief Economist
“Now is a good time to buy a home, if you can afford it. Prices keep climbing, which is pushing some buyers out of the market but giving those who remain an upper hand in negotiations. The conflict in the Middle East, elevated mortgage rates, and a volatile economy are making everyone wary, though, and local housing markets vary widely. Buyers serious about making offers should consult a local agent and be confident in their finances and future income.” – Daryl Fairweather, Redfin Chief Economist.
What buyers need to know about the housing market
Here are some key market trends to keep an eye on and help you make an informed homebuying choice. We’ll cover house prices, mortgage rates, supply, and demand, and inflation.
House prices are high and rising
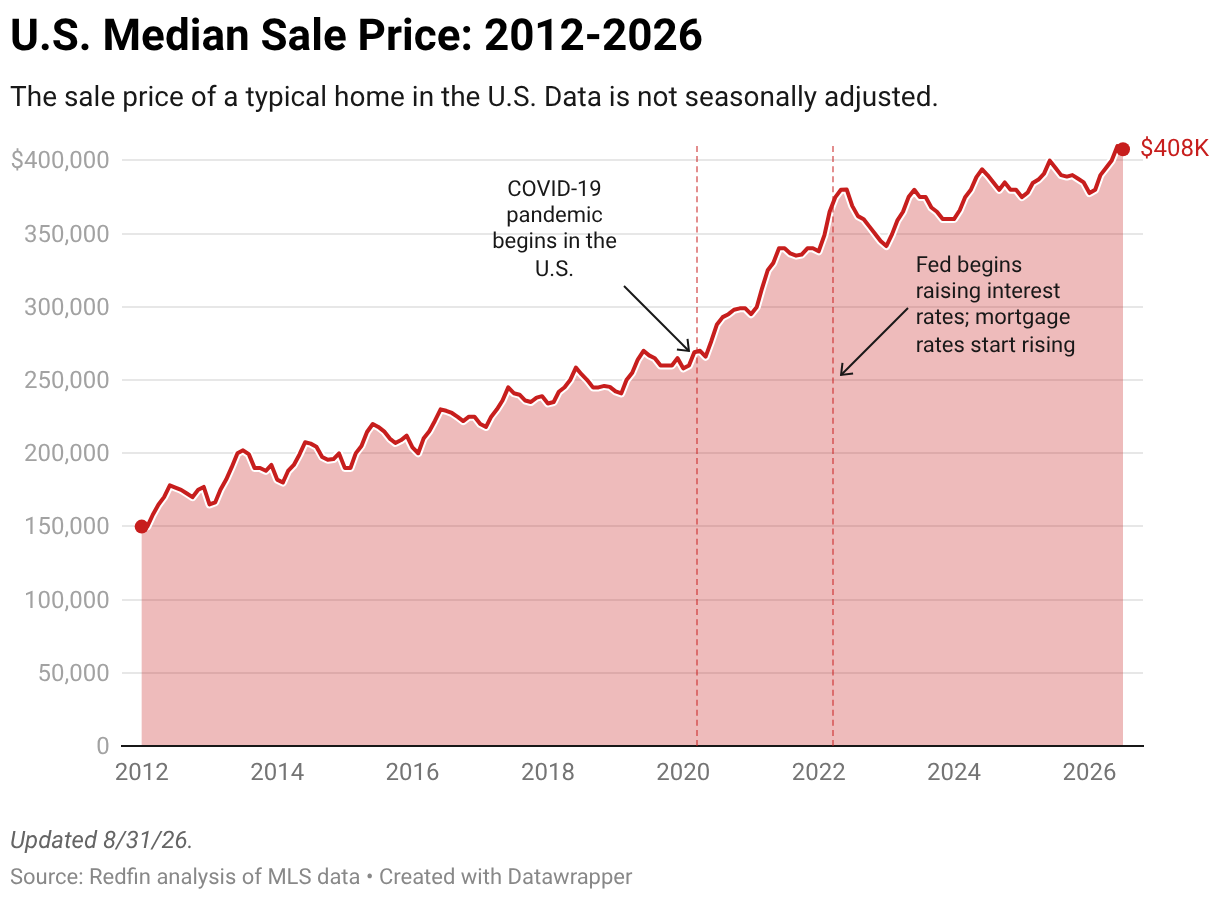
The median U.S. sale price is $407,730—up 3.2% from a year ago. House prices are nearly 20% higher than they were five years ago.
Because affordability has been so strained, many buyers and sellers have been holding out for better deals and higher offers, causing inventory to build up as they wait for the market to thaw. This push-pull dynamic has kept prices elevated, giving more affluent buyers a window of opportunity—especially the ultra-wealthy.
But in the last year, price growth has slowed as the market undergoes a prolonged and uneven reset. Home prices have grown by around 1.2% year-over-year since 2025, compared to ~7% growth from 2012 to early 2020. Prices have been growing more quickly in recent months, but Redfin predicts that affordability will still improve as wages outpace home price growth and inflation.
>> Read: Redfin’s Weekly Economic Breakdown
Mortgage rates remain elevated and volatile
As of August 31st, the weekly average 30-year fixed mortgage rate sits at 6.87%—the highest level in 14 months.
“Mortgage rates have continued to climb since March almost entirely because of the war in Iran and its effects on global energy prices, stock markets, and bond yields,” said Chen Zhao, Head of Economics Research at Redfin. “Markets are hoping for a peace deal to be struck, but optimism is thin as tensions flare and economic uncertainty weighs on everyone. Time will tell how the conflict will impact the U.S. economy and housing market, but so far it has put upward pressure on inflation and mortgage rates.”
Previously, rates had been trading between 6.1%-6.3% since late 2025. Redfin predicts that mortgage rates will average 6.3% for 2026.
There is some uncertainty surrounding mortgage rates, though. Because both inflation and the labor market have remained strong despite broader headwinds, many economists believe that the Fed will raise interest rates sometime this year, which will push up mortgage rates further.
>> Read: New Listings Hit 4-Month High While Demand Slips, Giving Serious Buyers Chance to Get a Deal Done
How mortgage rates affect housing costs
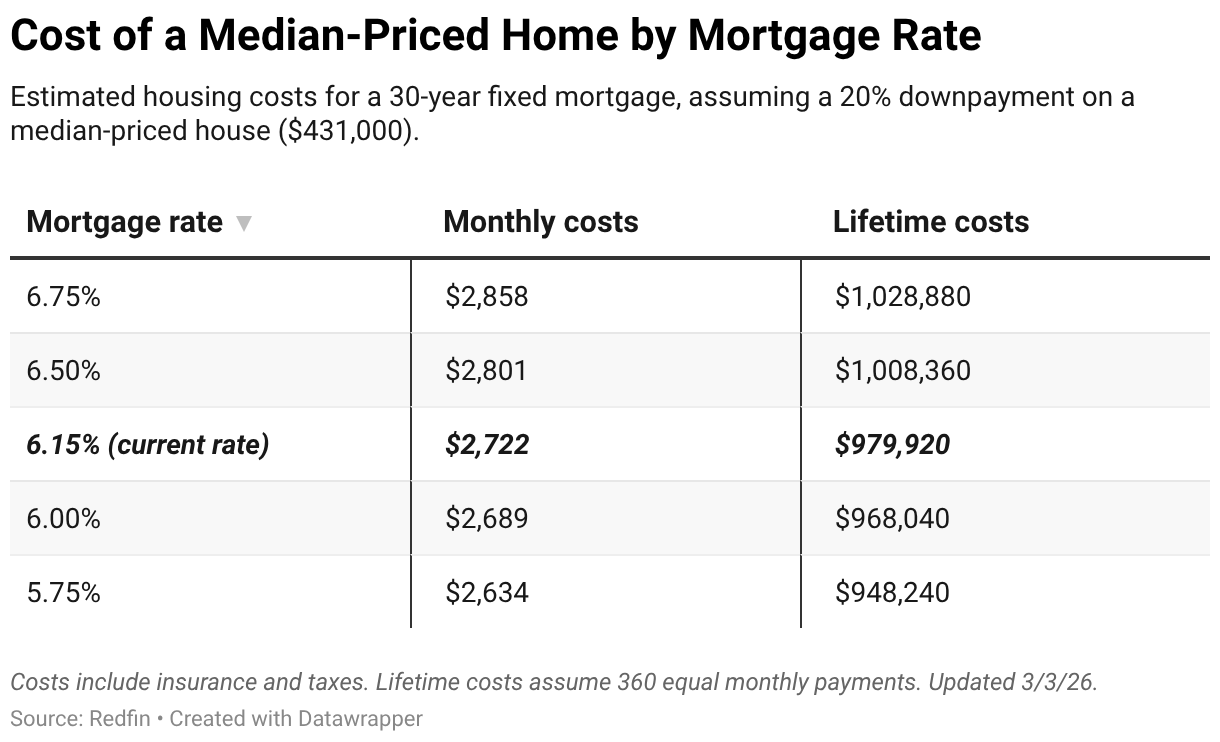
Mortgage rates are important for buyers because they directly translate to monthly housing costs. The higher the rate, the more you pay every month. If rates drop, you can save tens of thousands over the lifetime of your mortgage.
Let’s see how your monthly payments change with different rates, using data from our Mortgage Calculator.
Buyers have the upper hand
The housing market strongly favors buyers. Housing inventory has risen from its post-pandemic low—particularly in the Sun Belt—giving buyers more negotiating power. However, supply is still limited in small parts of the Midwest and East Coast, putting sellers in charge and pushing up prices.
In general, high costs are sidelining buyers and putting a lid on home sales.
Inventory is stalling
There are nearly 1.5 million homes for sale today—historically low but the highest monthly level since the pandemic. This is the primary driver behind today’s buyer’s market, giving homebuyers more leverage for concessions.
Housing inventory is high because a larger share of sellers are listing their homes than buyers are buying them, with the biggest imbalances in disaster-prone areas in Florida.
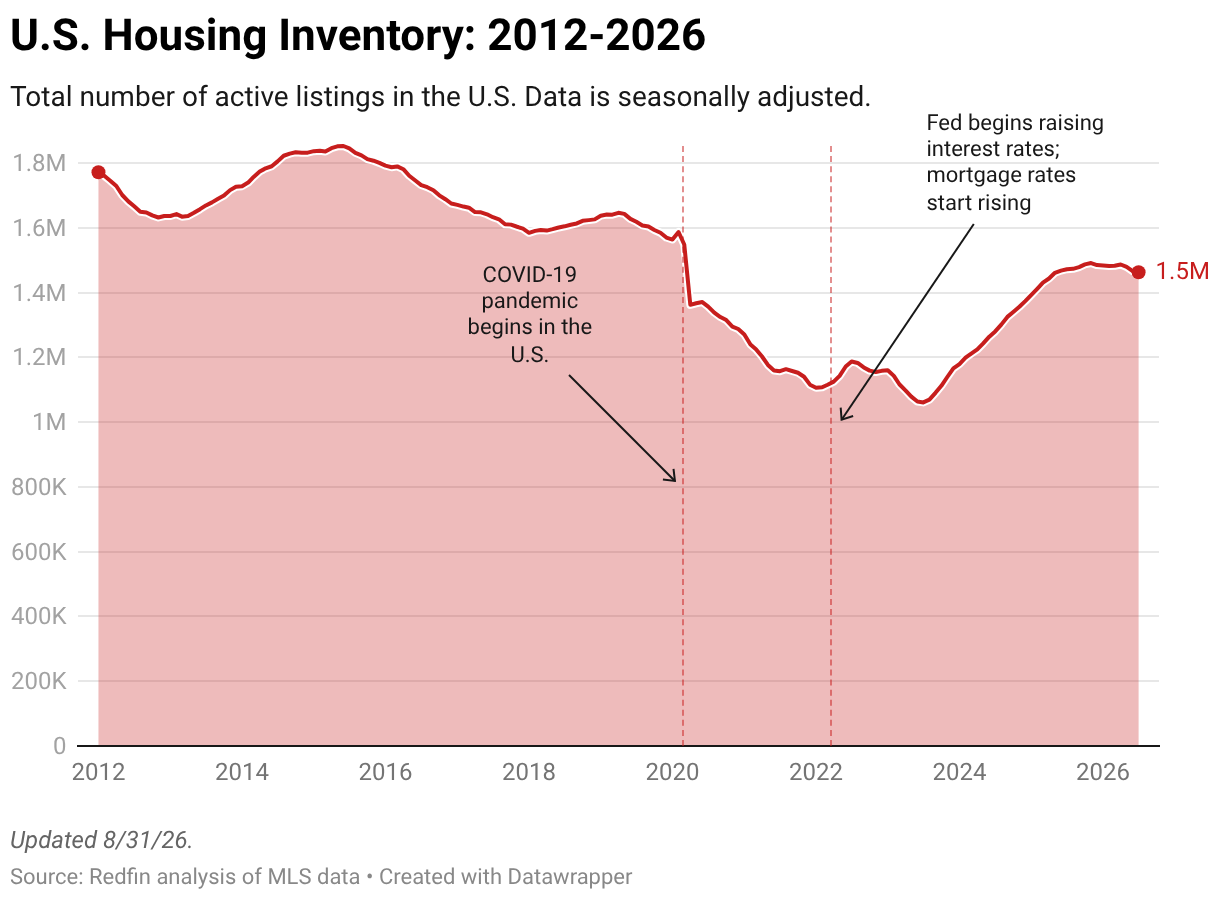
Listings were slowly rising to start the year, as homeowners looked to get a jump on the spring buying season. But since buyers have been harder to come by this spring and summer, some sellers are getting cold feet.
Demand is low
Homebuyers have been stuck on the sidelines for years waiting for affordability to improve, helping sellers far outnumber buyers in most parts of the country. As a result, demand continues to plummet: Touring activity is down, sales are dropping, more deals are falling through, and a majority of listings have been sitting on the market for nearly two months.
However, there is a bright spot: The typical asking price for a home recently dropped to its lowest level in a year, suggesting that sellers are adjusting their expectations and no longer pricing like it’s 2021. For buyers with the budget, this could still be a good time to enter the market.
Buyers have the most leverage in Sun Belt metros, where inventory has surged thanks to new construction—especially Austin, which is now the slowest major housing market in America. But there are still pockets of competition. In New York metros like Rochester and Buffalo, strong demand for affordable homes continues to push up prices and put sellers in charge. The Bay Area has also seen a surge in popularity, along with parts of the Midwest.
>> Read: NYC Suburbs and the Bay Area Are the Most Competitive Housing Markets
How to buy in an uncertain economy
With tariffs, economic whiplash, and volatile mortgage rates, many buyers are wary of getting into the market. Here are a few tips from our economists about navigating this shifting landscape.
- Stick to your budget: This isn’t the time to stretch financially. Recession odds are lower than they have been, but the economy is still unstable. Make sure you have enough in savings to cover mortgage payments if your income changes.
- Negotiate, negotiate: The market favors buyers, so use your leverage. There’s more inventory, and offers are increasingly coming in below asking.
- Be smart about rates: Mortgage rates are elevated and unstable. Shop around, compare lenders, and ask about “float down” options if rates drop significantly after you lock in.
- Sell before you buy: If you own a home, consider selling it first. It will give you a clearer budget and help you avoid the risk of carrying two mortgages.
>> Read: How to Buy, Sell, or Rent a Home Amid Economic Uncertainty
Are you ready to buy and own a house?
When deciding whether to buy a home in today’s climate, you’ll want to think beyond market conditions and focus on your individual circumstances. Here are some personal considerations to keep in mind.
Financial health
Take stock of your current savings, credit score, and debt levels. Can you afford a house? Or does renting make more sense?
Housing is a long-term commitment, so you’ll want a solid emergency fund—ideally covering 3 to 6 months of expenses—for maintenance and unexpected costs.
Monthly budget
Determine how a mortgage payment at today’s rates might impact your lifestyle. Make sure you can comfortably handle monthly payments, property taxes, insurance, and other homeownership expenses.
Job and location stability
Buying a house makes sense if you plan to stay put for several years. A stable job or reliable income is crucial to avoid financial strain, especially if home prices or interest rates rise further.
Choosing your location is also essential. Is your potential home prone to flooding, wildfires, or other climate risks? This is especially important today, as insurers continue dropping homeowners at alarming rates.
Personal goals and timelines
Think about life events, like starting a family, retiring, or relocating. These factors can make owning a home either more appealing or potentially riskier if you need to move soon.
Lifestyle preferences
Homeownership comes with ongoing responsibilities, like maintenance, repairs, and property taxes. Ask yourself if you have the time, resources, and a desire to handle them.
>> Read: Am I Ready to Buy a House?
So, is now a good time to buy a house?
If you have the means and are ready to own a home, now is a good time to buy a house. Rates are volatile, and with today’s high prices and uncertain economy, it’s hard to know what affordability will look like down the line. But waiting for rates to fall leaves you at risk of competition among buyers and subsequent price hikes from sellers.
In a market this unpredictable, the best approach is to be prepared. Know your budget, connect with a local agent, get preapproved for a mortgage, and move quickly when the right home comes along. The longer you wait, the more competition you could see.